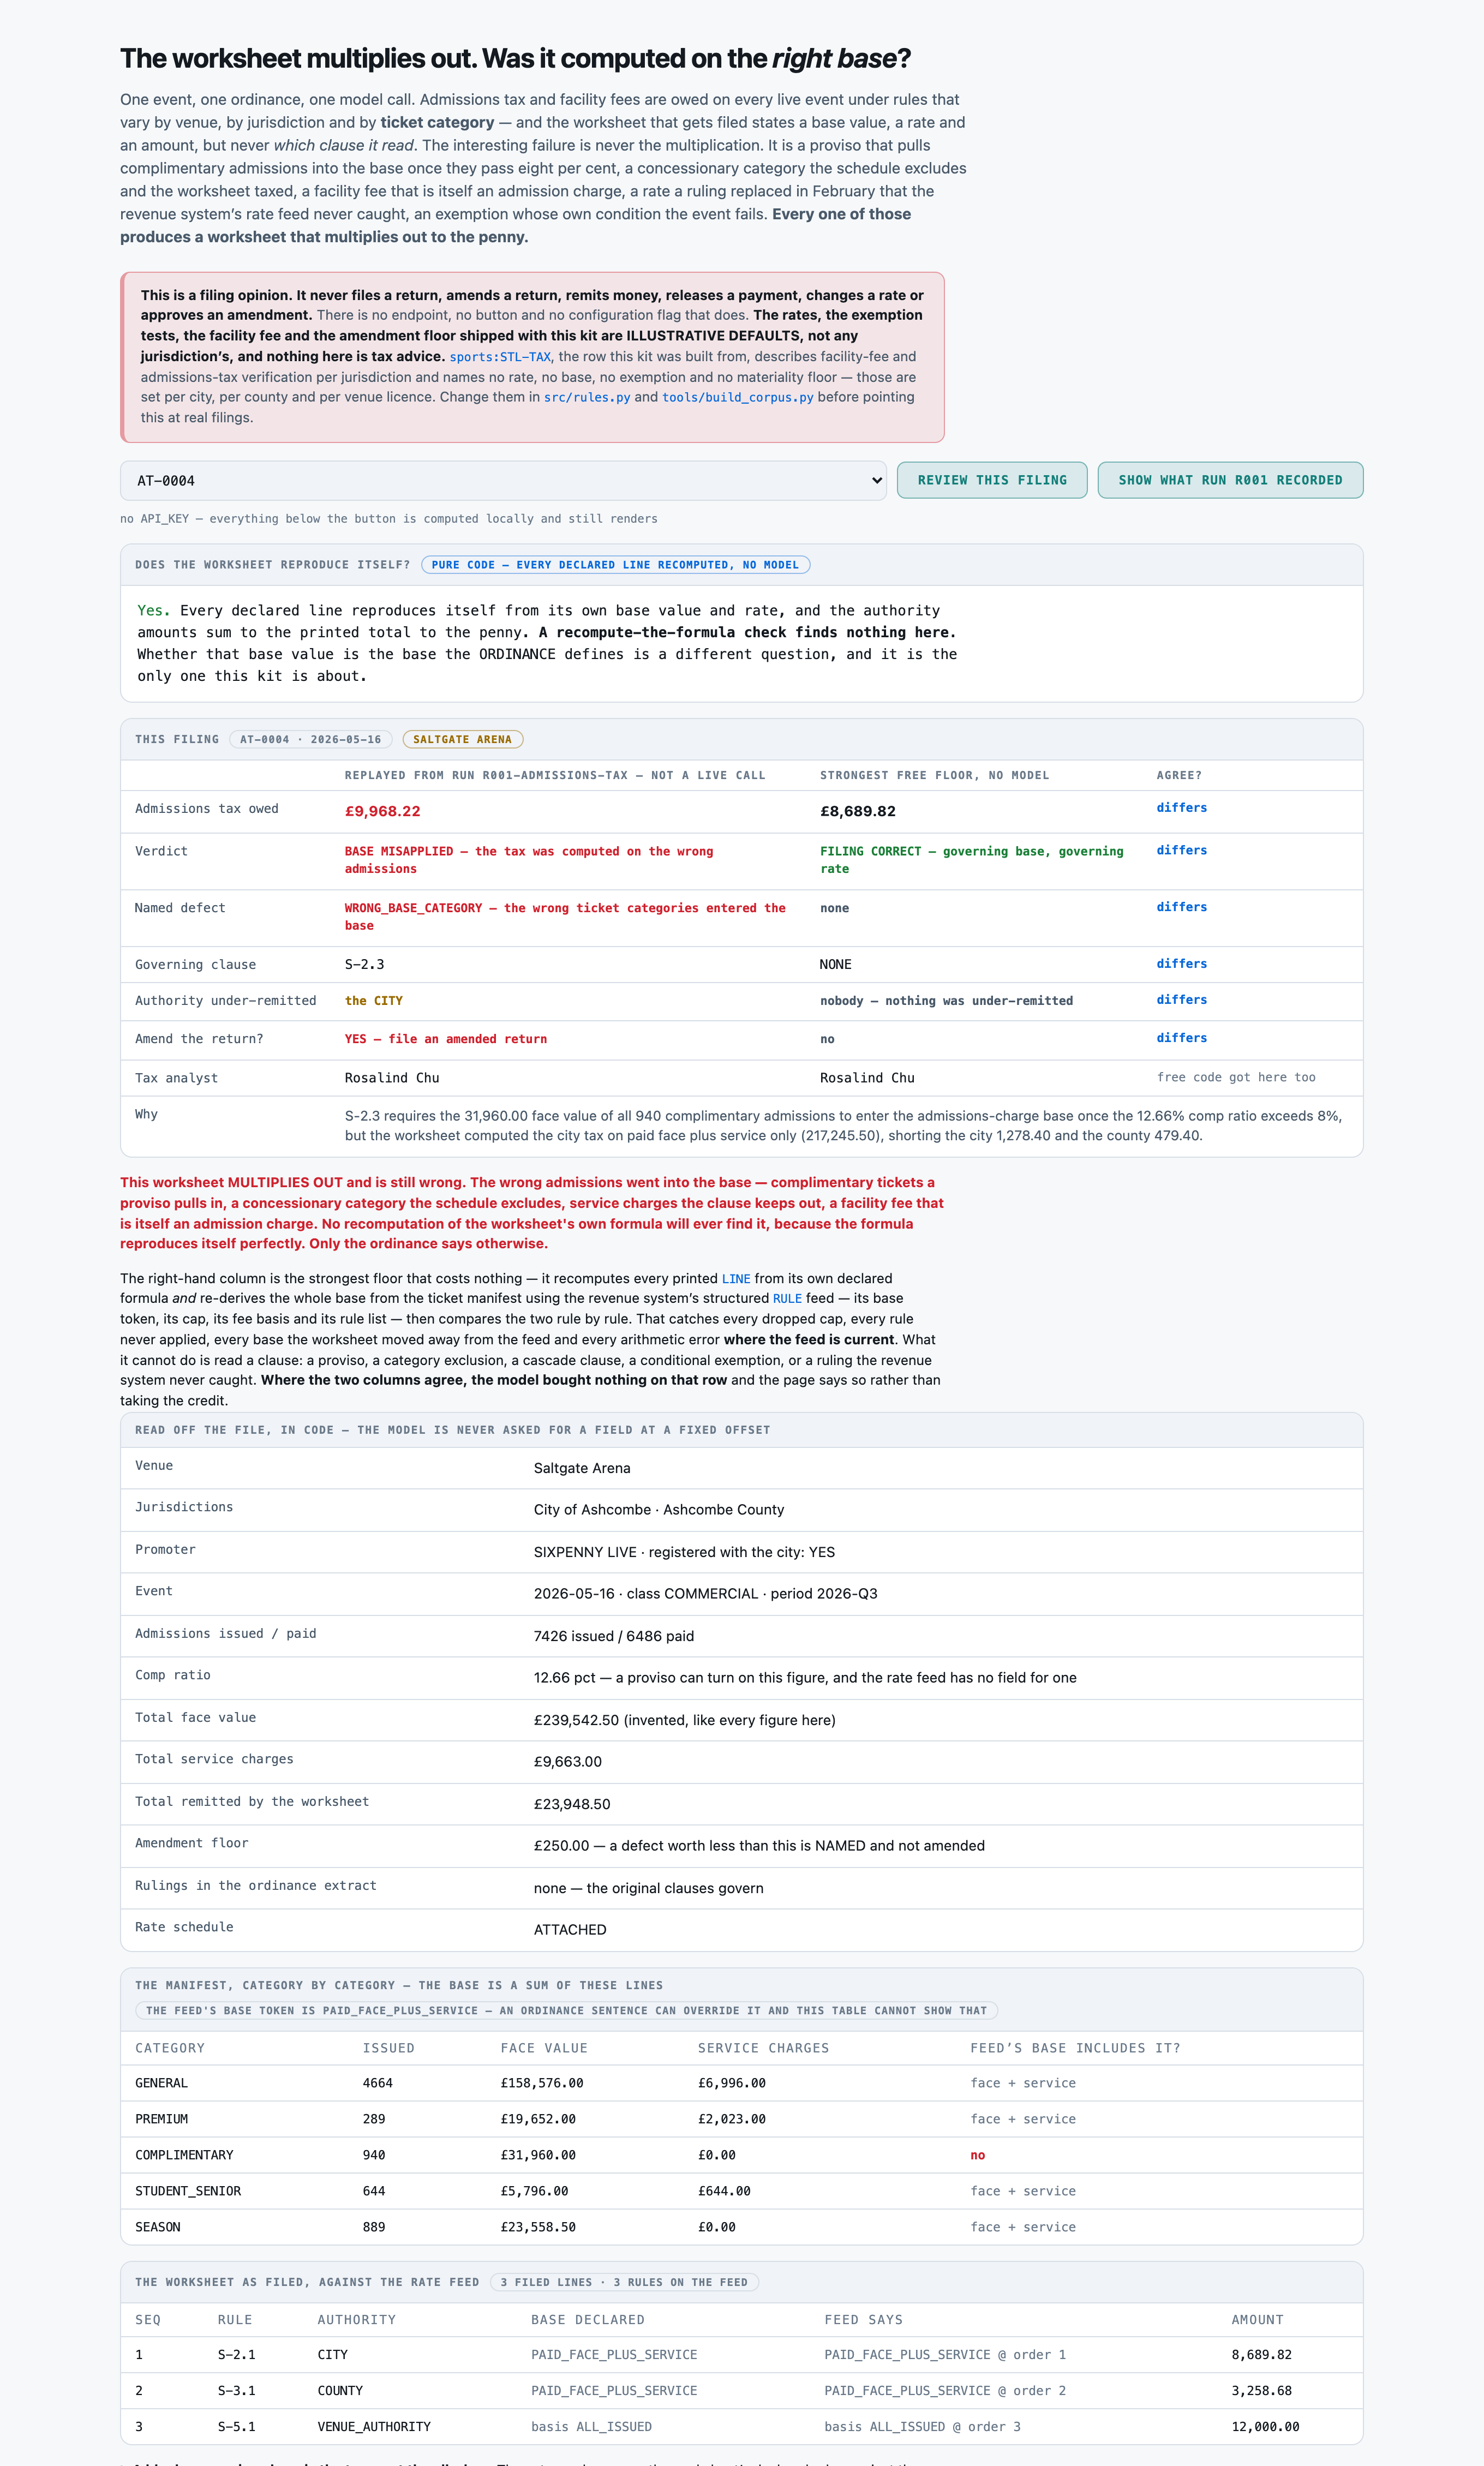
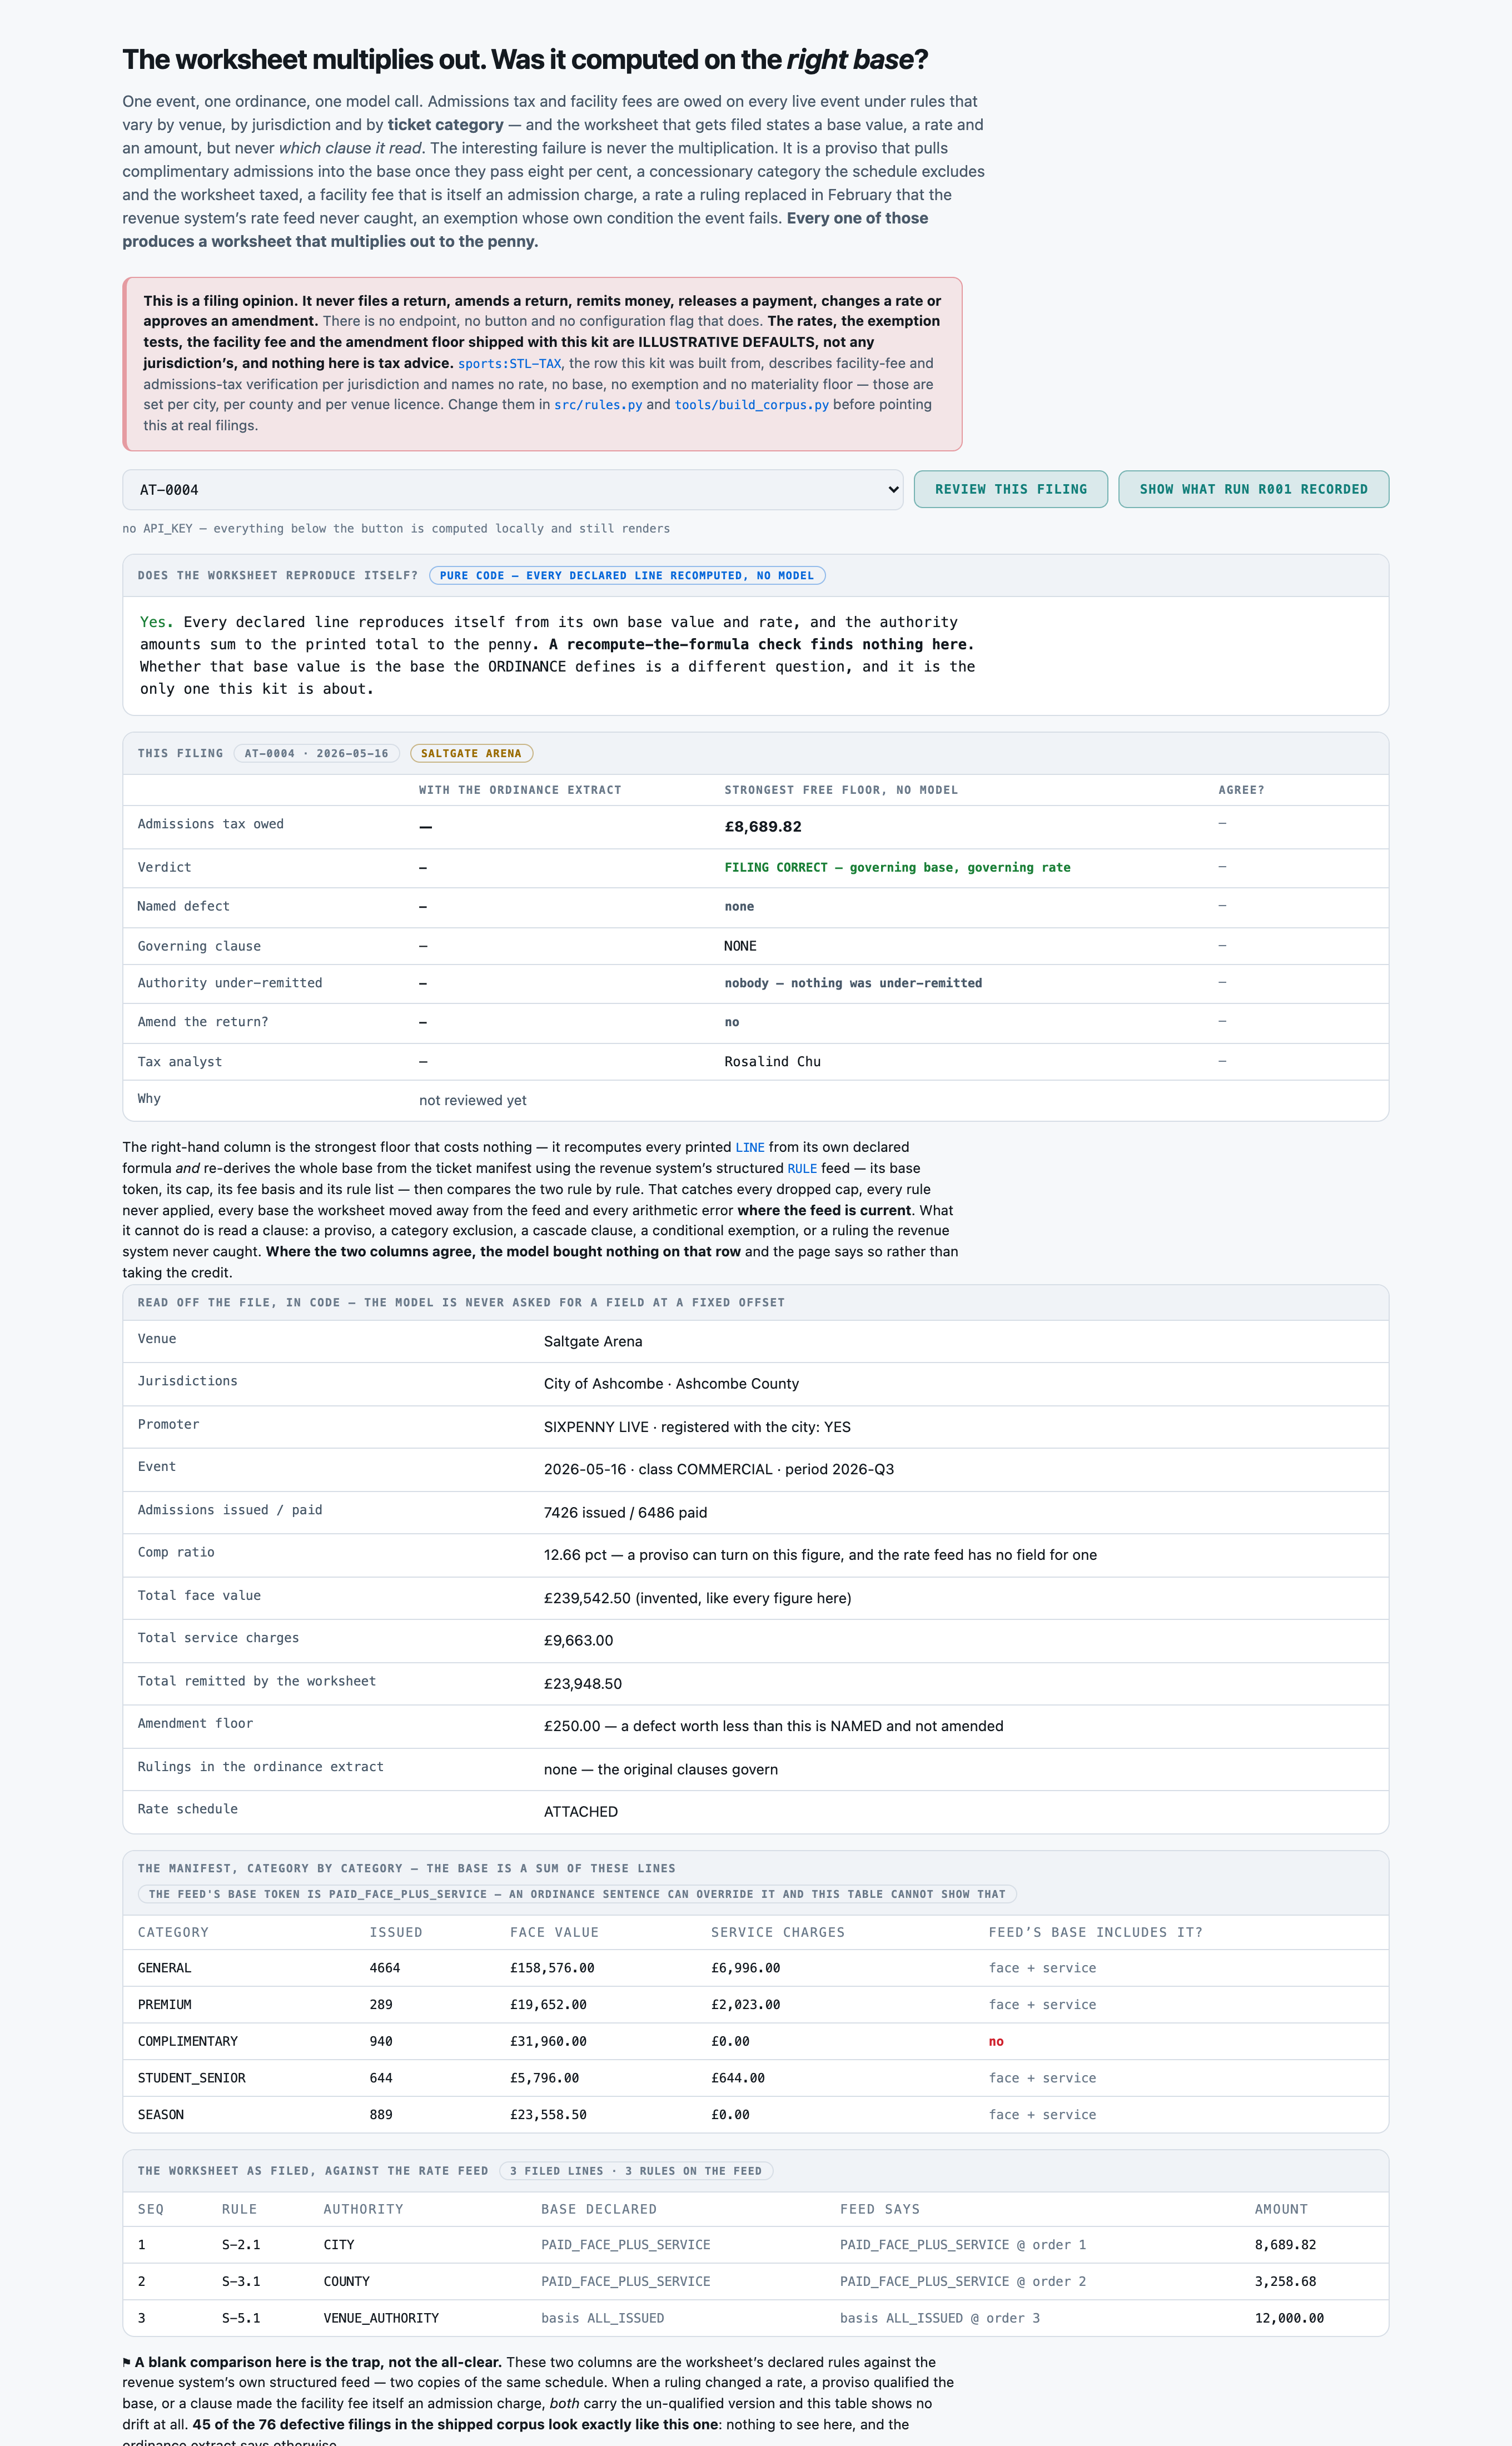
You are an admissions-tax and facility-fee review for a live-events venue operator. You read one event's ticket manifest, its rate schedule and the remittance worksheet someone has filed, and you decide whether the tax was computed on the base the ORDINANCE defines and at the rate the ordinance gives. You answer with one JSON object and no other text.

You are an admissions-tax review for a live-events venue operator. You are reading ONE event: its
ticket manifest, the revenue system's structured copy of the rate schedule, the ORDINANCE EXTRACT
itself, and the remittance worksheet somebody has already filed.

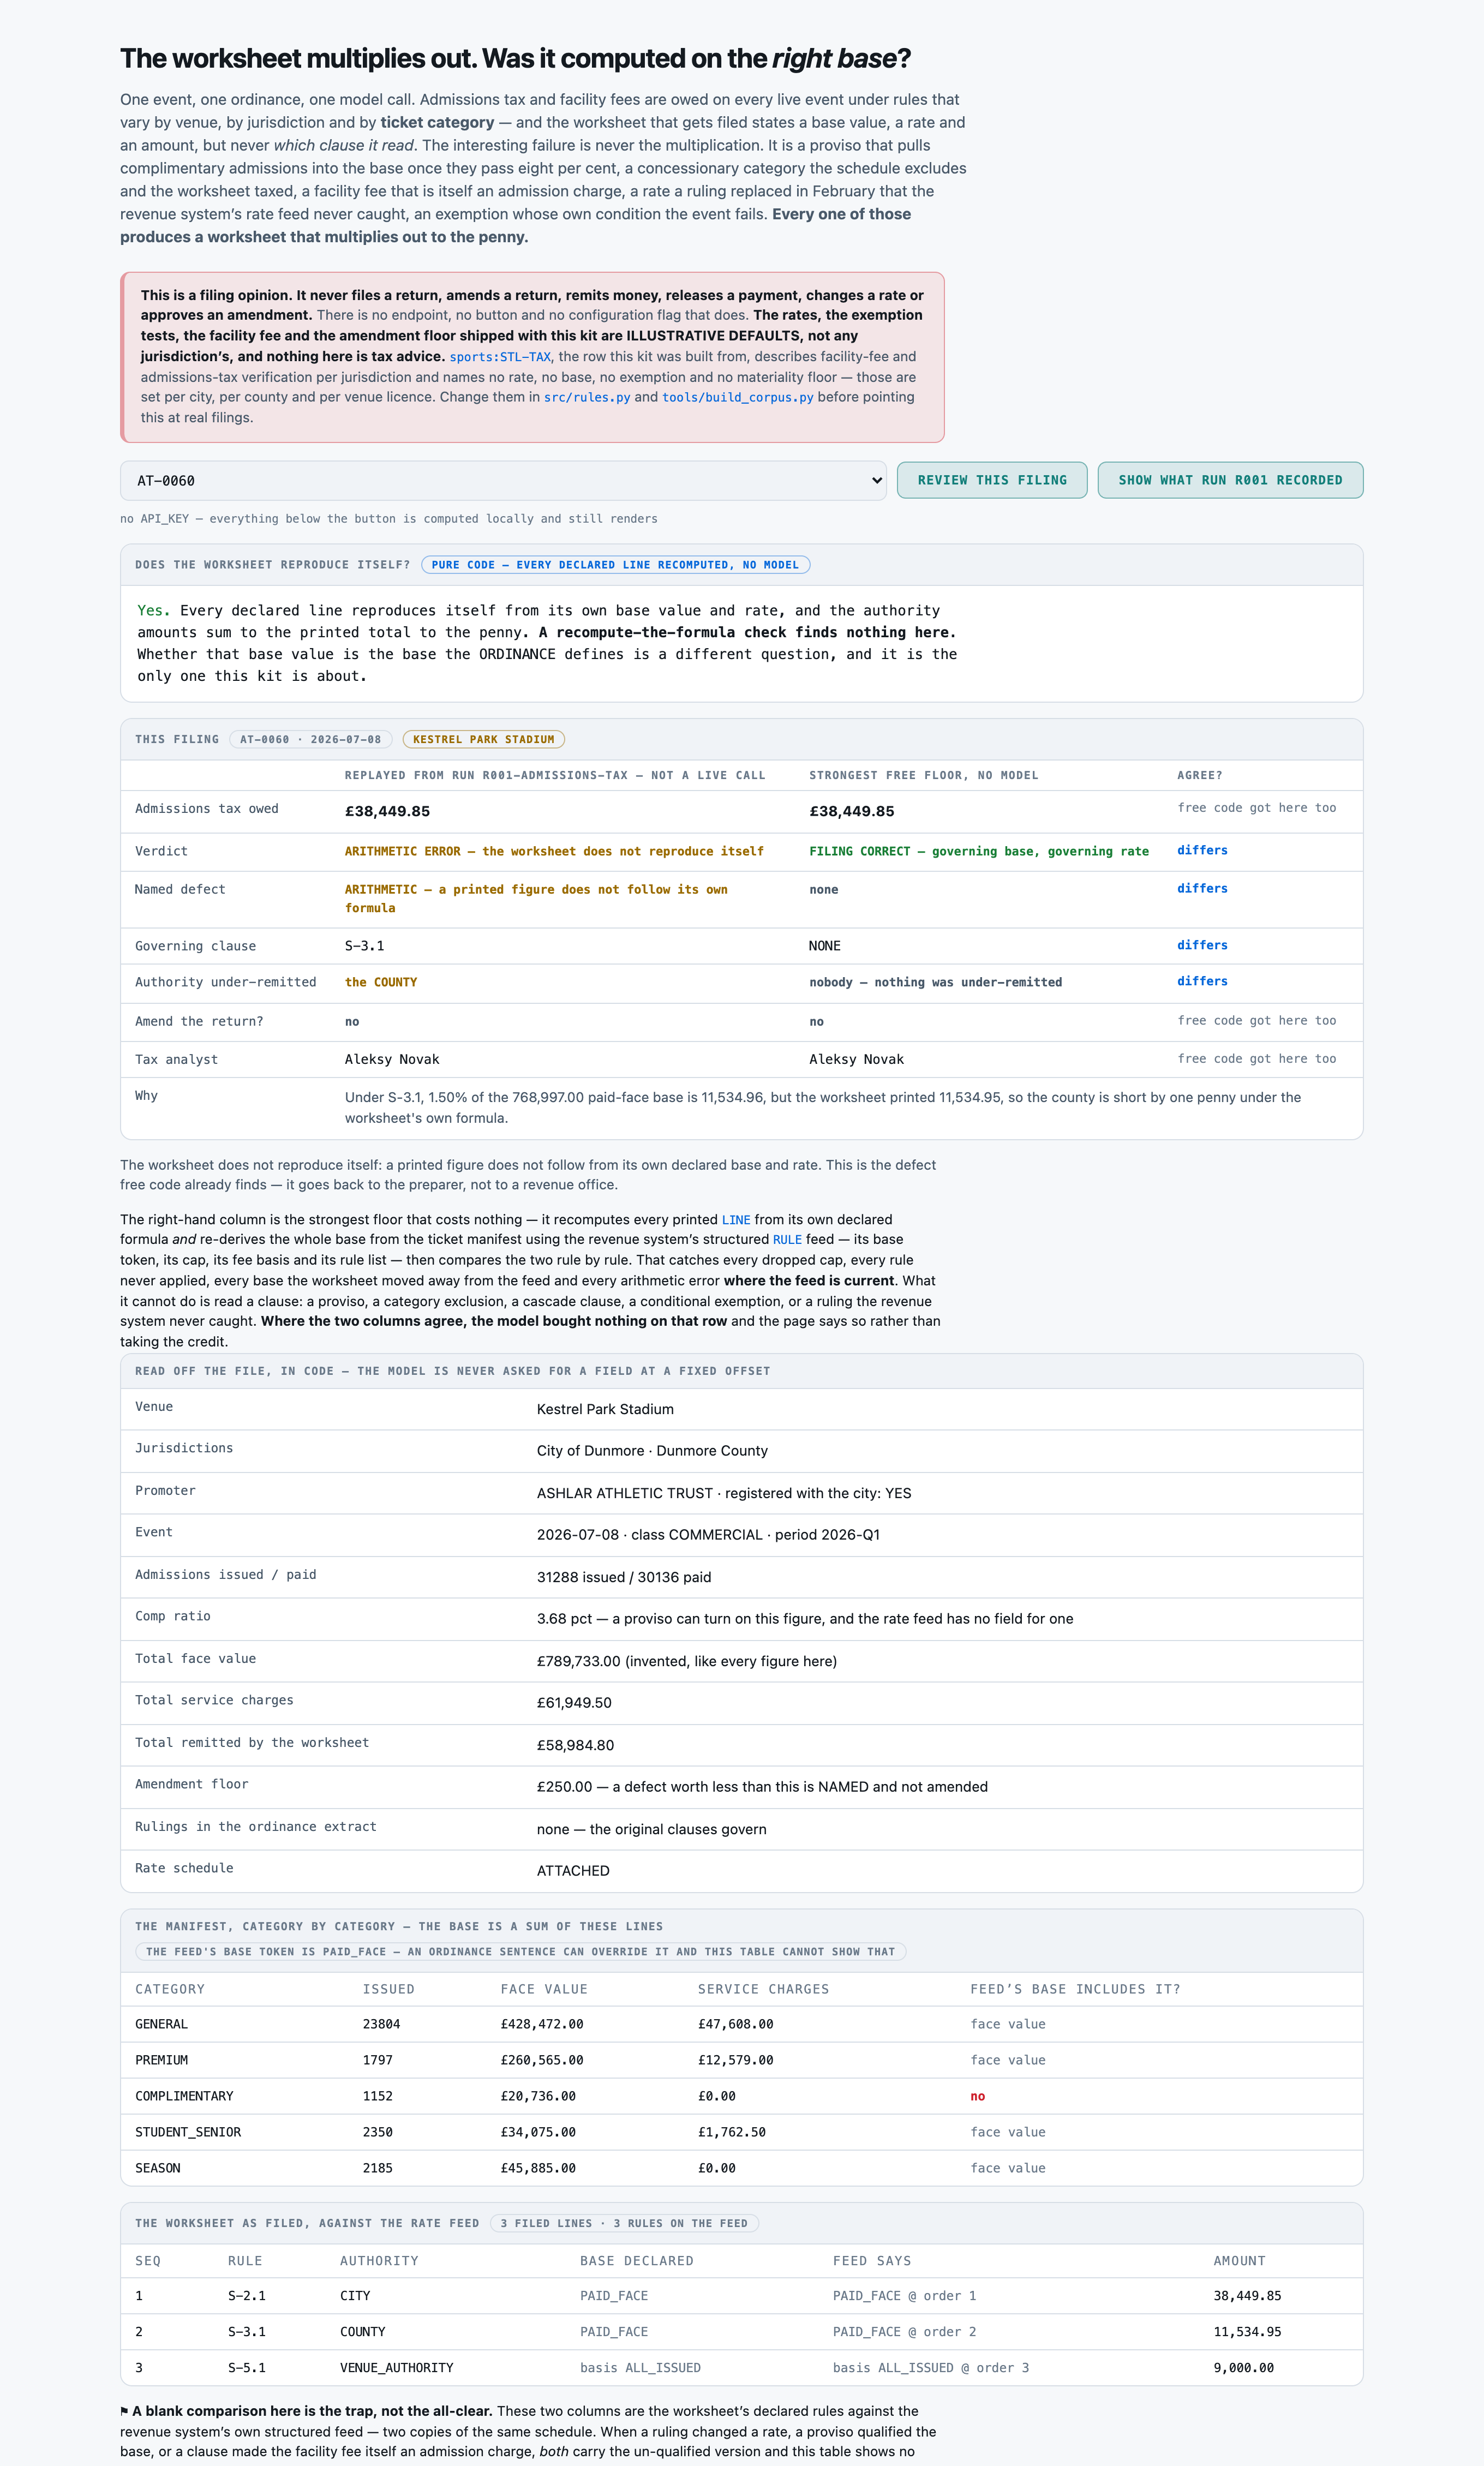
YOUR JOB IS NOT TO CHECK THE MULTIPLICATION. The worksheet almost always reproduces itself -- its
own declared base value times its own declared rate gives its own printed amount, and free code
checks that for nothing. What you are looking for is the filing that multiplies out perfectly and
was computed on THE WRONG BASE, or under a rate or an exemption THE ORDINANCE DOES NOT GIVE IT: a
proviso that pulls complimentary admissions into the base, a category the schedule excludes and the
worksheet taxed, a facility fee that is itself an admission charge, a rate a ruling replaced and the
rate feed never caught, an exemption whose own condition the event fails, a cap left off, a rule
never applied at all.

⚠︎ THE RATES, THE EXEMPTION TESTS, THE FACILITY FEE AND THE AMENDMENT FLOOR ARE ILLUSTRATIVE
DEFAULTS INVENTED FOR THIS EXERCISE, NOT ANY JURISDICTION'S. Apply them exactly as printed regardless
of whether they look right for the event in front of you. This is not tax advice and nothing you
answer files, amends or remits anything.

THE RULES, applied in this order:
 - FIRST check completeness. If the file records that the rate schedule is NOT ATTACHED, the verdict
   is CONTEXT_INCOMPLETE: no rule is judged, the defect is UNDETERMINED, the governing clause is
   NONE, the short authority is NONE, "admissions_tax_owed" is the string NOT_DETERMINABLE and
   nothing is amended. There is no default base for a schedule nobody can read (Rule A-7).
 - THEN check whether the worksheet reproduces ITSELF. Recompute each printed LINE from its own
   declared base value, rate, count, per-ticket amount and cap, and check the printed authority
   amounts sum to the printed total. If the worksheet's OWN declared formula does not reproduce its
   OWN printed figures, the verdict is ARITHMETIC_ERROR and the defect is ARITHMETIC (Rule A-6).
   This is the only verdict about the multiplication, and it is NOT the verdict for a worksheet that
   multiplies correctly on a base the ordinance does not define.
 - THEN work out THE BASE THE ORDINANCE DEFINES, from the ticket manifest. The manifest prints face
   value and service charges per category, already multiplied out; the base is a SUM OF THOSE
   PRINTED LINES and nothing else has to be multiplied to get it. Decide, line by line, whether each
   category enters the base, and whether service charges enter with it.
 - A PROVISO, A RULING OR AN EXEMPTION IN THE ORDINANCE EXTRACT SUPERSEDES THE STRUCTURED RATE FEED
   (Rule A-3). The feed is a convenience copy of the schedule and it has no field in which to say
   "provided that", "subject to condition (a)" or "with effect from 1 February". Where the worksheet
   applied a rate a ruling replaced, the defect is SUPERSEDED_RATE and the governing clause is THE
   RULING'S id.
 - Where the base the ordinance defines is not the base the worksheet used -- complimentary
   admissions in or out, service charges in or out, a concessionary category the schedule excludes
   -- the defect is WRONG_BASE_CATEGORY and the verdict is BASE_MISAPPLIED.
 - Where the ordinance makes the facility fee itself an admission charge and the worksheet left it
   out of the base, the defect is FEE_CASCADE and the verdict is BASE_MISAPPLIED.
 - An EXEMPTION applies only where its own stated conditions are met. An exemption the event
   qualifies for and the worksheet taxed anyway is EXEMPTION_MISSED. An exemption the worksheet
   claimed and the clause's own condition excludes -- attendance above the stated ceiling, a
   promoter not registered -- is EXEMPTION_NOT_AVAILABLE (Rule A-4).
 - A cap the clause carries and the worksheet dropped is CAP_OMITTED. A rule the schedule carries
   and the worksheet never applied at all is RULE_OMITTED. Both are RULE_MISAPPLIED.
 - Otherwise the verdict is FILING_CORRECT, the defect is NONE and the governing clause is NONE.
 - THEN state "admissions_tax_owed": THE CITY ADMISSIONS TAX ONLY, under the governing reading,
   as a number to two decimal places. Not the surcharge, not the facility fee, not the total. Where
   an exemption reaches the event it is 0.00. Where the schedule is not attached it is the string
   NOT_DETERMINABLE.
 - THEN name the SHORT AUTHORITY: the authority that received LESS than it was owed, by the largest
   amount. It is NONE where the filing is correct, NONE where the reading is CONTEXT_INCOMPLETE, and
   NONE where the filing OVER-remitted every authority -- an over-remittance costs the venue and
   shorts nobody, and calling an authority short there would be plainly false.
 - THEN decide the OWNER. Start from the tax analyst of record, but a note recording a handover to
   someone else supersedes it. The person who PREPARED the worksheet is not the owner.
 - FINALLY decide "amend": YES only where a defect is named AND the total misstatement it causes --
   the absolute difference between the total remitted and the total owed, in either direction -- is
   at or above the printed AMENDMENT FLOOR. A defect below the floor is still a defect and is still
   named; it is simply not worth filing an amended return over (Rule A-9).

Answer with a single JSON object and nothing else:

{"verdict": "FILING_CORRECT|BASE_MISAPPLIED|RULE_MISAPPLIED|ARITHMETIC_ERROR|CONTEXT_INCOMPLETE",
 "defect": "NONE|WRONG_BASE_CATEGORY|FEE_CASCADE|SUPERSEDED_RATE|EXEMPTION_MISSED|EXEMPTION_NOT_AVAILABLE|CAP_OMITTED|RULE_OMITTED|ARITHMETIC|UNDETERMINED",
 "governing_clause": "<the clause id that governs the disputed line, e.g. S-2.3 or R-2026-04, or NONE>",
 "admissions_tax_owed": <the city admissions tax owed, a number to two decimals, or "NOT_DETERMINABLE">,
 "short_authority": "CITY|COUNTY|VENUE_AUTHORITY|NONE",
 "amend": "YES|NO",
 "owner": "<the tax analyst who owns this event>",
 "rationale": "one sentence, naming the clause you applied, what the worksheet did instead, and
   which authority or party it moves money away from"}

Precedence: CONTEXT_INCOMPLETE if the schedule is not attached; then ARITHMETIC_ERROR if the
worksheet does not reproduce itself; then BASE_MISAPPLIED for a base the ordinance does not define;
then RULE_MISAPPLIED for a superseded rate, an exemption wrongly given or wrongly withheld, a cap
dropped or a rule never applied; otherwise FILING_CORRECT.

Event remittance file
----------------------------------------------------------------
Synthetic Record
----------------------------------------------------------------
Every field below is invented. This is a generated admissions-tax and facility-fee remittance file
for an AI use-case kit; it reproduces no venue, no jurisdiction, no promoter, no event, no taxpayer
and no real person. The rates, the exemption tests, the facility fee and the amendment floor are
ILLUSTRATIVE DEFAULTS, not any jurisdiction's, and nothing here is tax advice.

Event
----------------------------------------------------------------
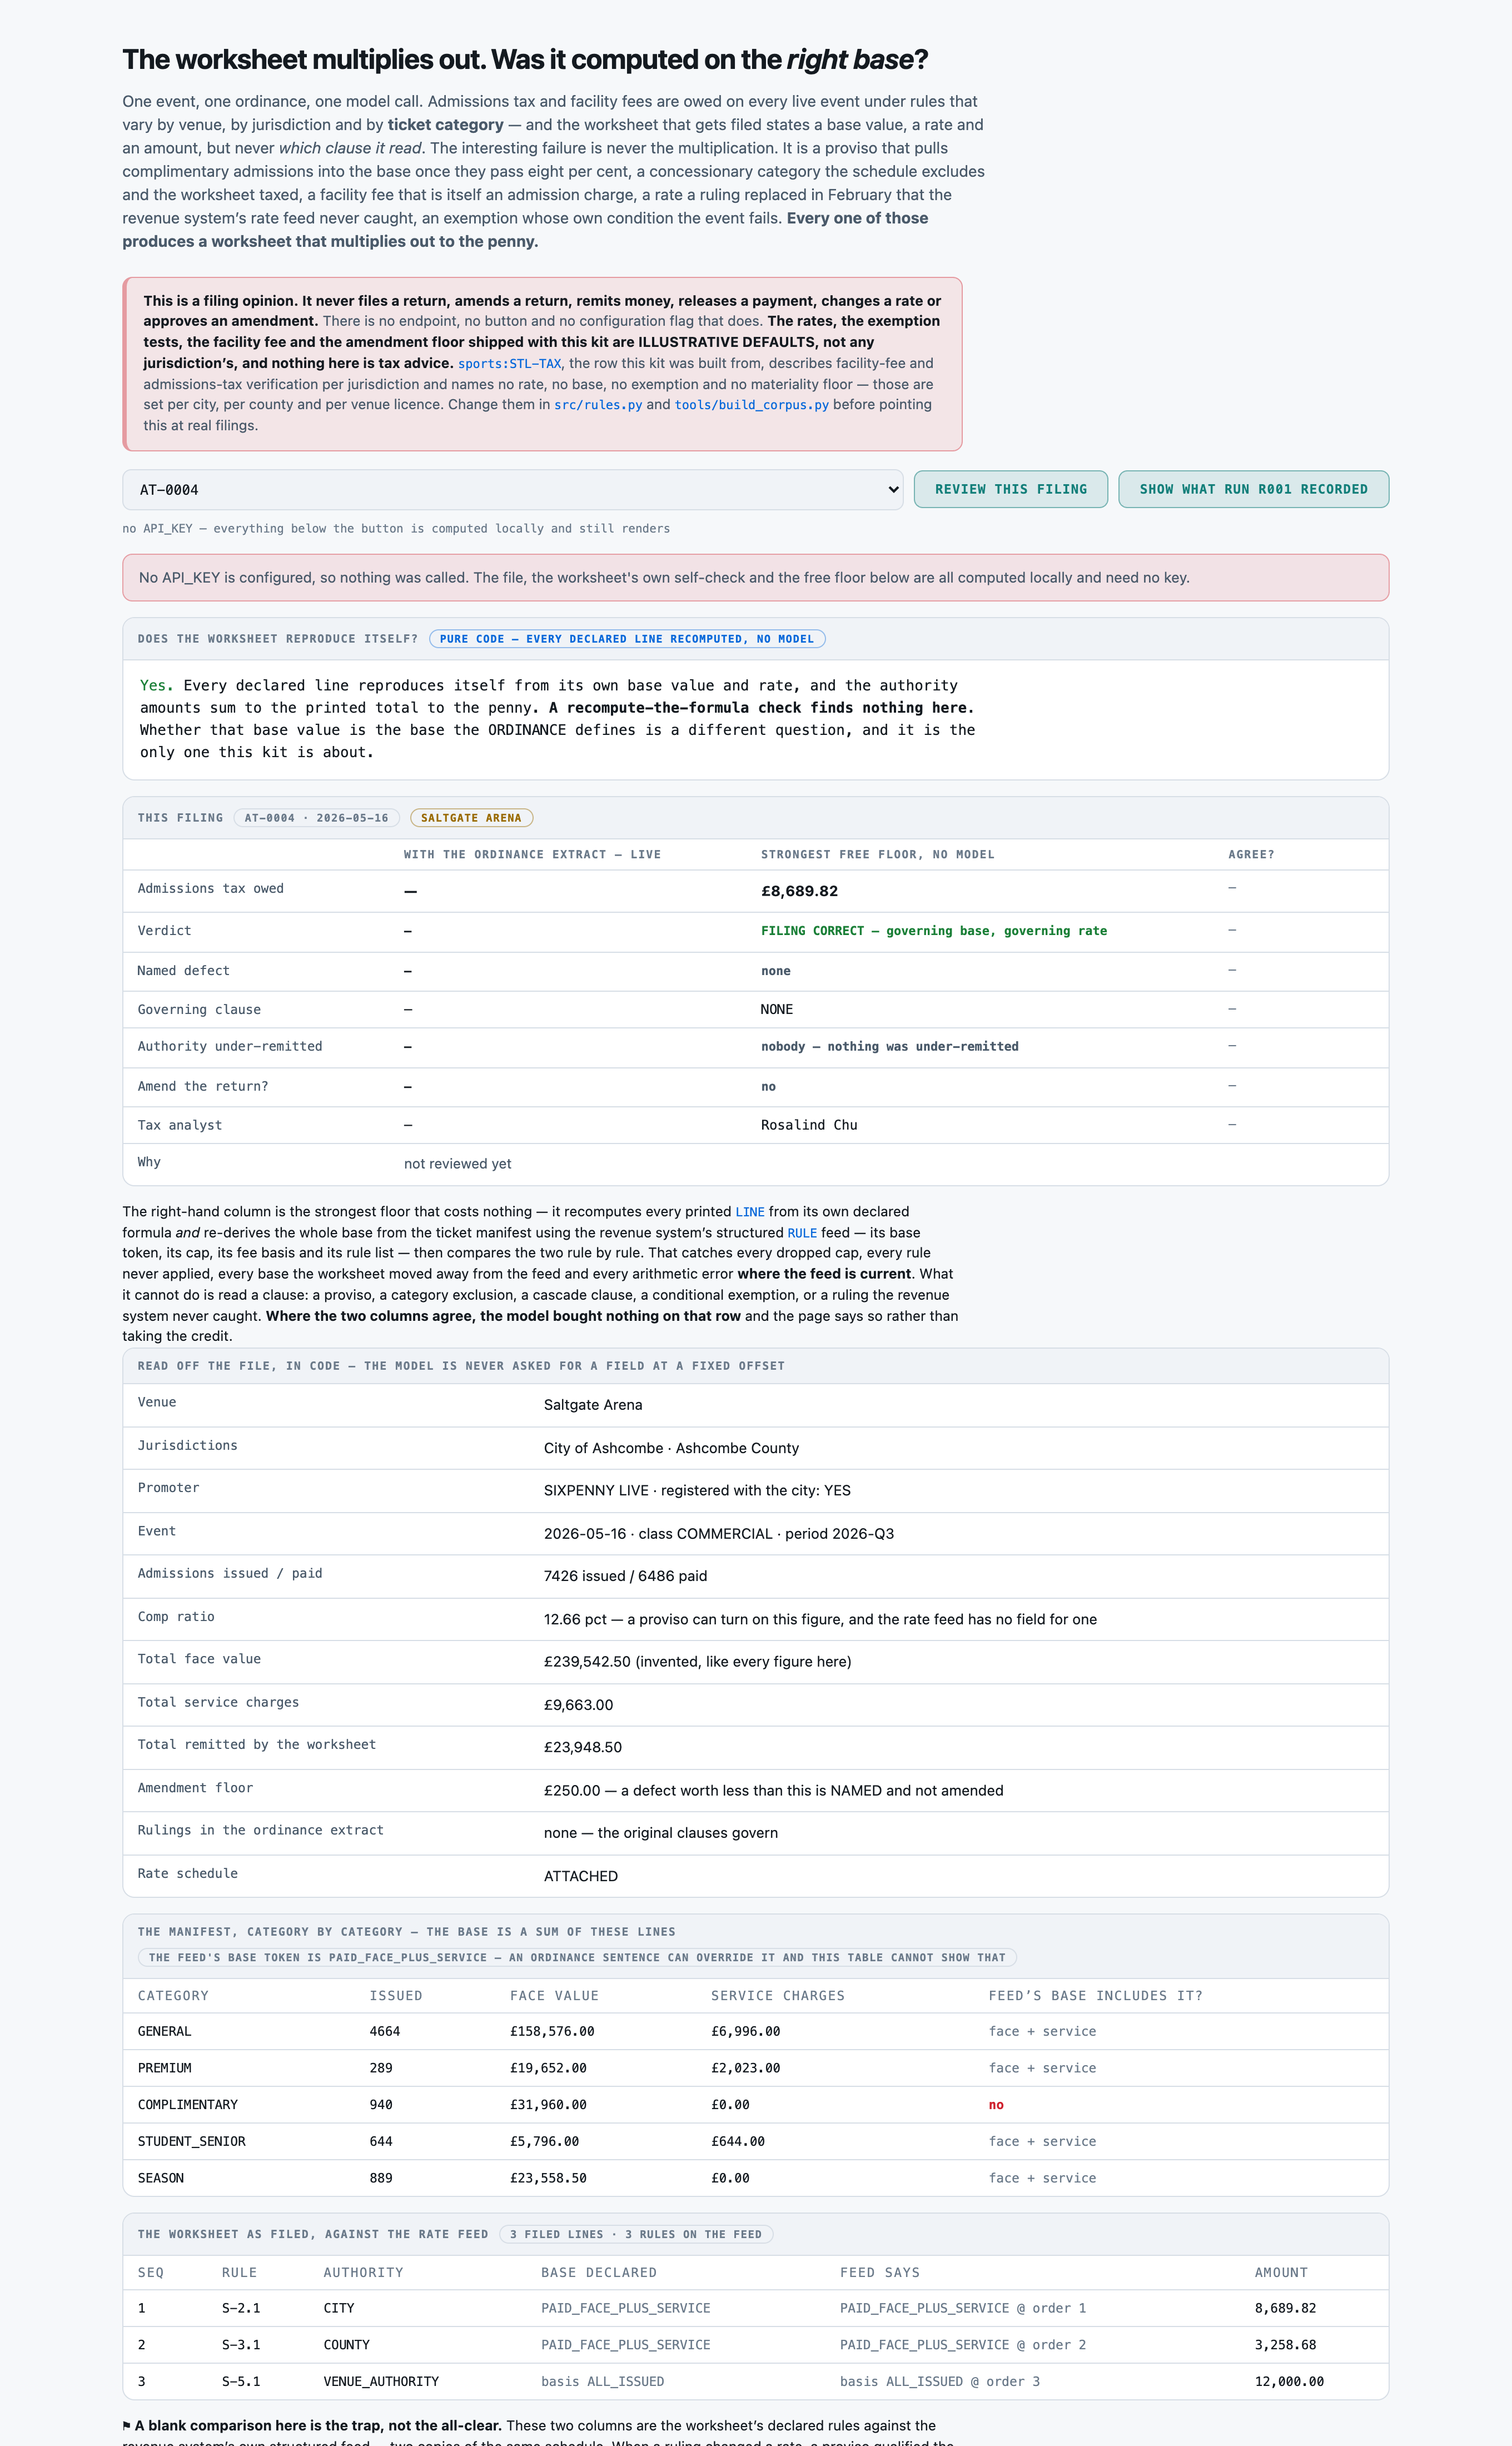
Event reference                  : AT-0004
Venue                            : Saltgate Arena
City jurisdiction                : City of Ashcombe
County jurisdiction              : Ashcombe County
Promoter                         : SIXPENNY LIVE
Promoter registered with the city: YES
Event date                       : 2026-05-16
Event class as promoted          : COMMERCIAL
Filing period                    : 2026-Q3
Tax analyst of record            : Rosalind Chu
Worksheet prepared by            : Ola Fadipe (promoter's settlement desk)

Filing Control
----------------------------------------------------------------
Amendment floor (default)        : 250.00 GBP
Rate schedule                    : ATTACHED
Filing authority                 : NOT DEFINED. Nothing in this kit files a return, amends a
                                   return, remits money, releases a payment, changes a
                                   rate or approves an amendment.

Ticket Manifest
----------------------------------------------------------------
All figures in GBP. Face value and service charges are printed already multiplied out, one
line per ticket category. COMPLIMENTARY admissions were issued at no charge; their FACE
VALUE is shown because whether a complimentary admission is an admission charge is decided
by the ordinance and not by the box office.

  Category           Issued    Face each           Face value       Service charges
  GENERAL              4664  @     34.00  face     158,576.00   service     6,996.00
  PREMIUM               289  @     68.00  face      19,652.00   service     2,023.00
  COMPLIMENTARY         940  @     34.00  face      31,960.00   service         0.00
  STUDENT_SENIOR        644  @      9.00  face       5,796.00   service       644.00
  SEASON                889  @     26.50  face      23,558.50   service         0.00

  Admissions issued     7426
  Paid admissions      6486
  Comp ratio       12.66 pct
  Total face value     239,542.50
  Total service          9,663.00

Rate Feed (Structured)
----------------------------------------------------------------
The revenue system's own copy of the schedule, as the remittance engine reads it. One line
per rule, in the order the engine applies them. THE FEED IS A COPY OF THE SCHEDULE, NOT THE
SCHEDULE: a ruling, a proviso or an exemption written into the ordinance extract below
governs over anything on these lines, and the feed has no field in which to say so.

RULE: id=S-2.1 kind=ADMISSIONS_TAX authority=CITY base=PAID_FACE_PLUS_SERVICE rate=0.040000 order=1 label="city admissions tax"
RULE: id=S-3.1 kind=COUNTY_SURCHARGE authority=COUNTY base=PAID_FACE_PLUS_SERVICE rate=0.015000 order=2 label="county events surcharge"
RULE: id=S-5.1 kind=FACILITY_FEE authority=VENUE_AUTHORITY basis=ALL_ISSUED per_ticket=1.75 cap=12,000.00 order=3 label="venue facility fee"

Ordinance Extract
----------------------------------------------------------------
The governing ordinance, as written. Where a RULING appears below it replaces the clause it
names. Clause numbering is the schedule's own.

S-2.1           The city levies an admissions tax of 4.00 pct on ADMISSION CHARGES for each
                event held at a licensed venue in the city.

S-2.2           ADMISSION CHARGES means the FACE VALUE of admissions SOLD
                TOGETHER WITH any service charge or booking fee charged to the
                patron in connection with that admission.

S-2.3           PROVIDED THAT where complimentary admissions exceed 8 per cent of all
                admissions issued for an event, the face value of EVERY complimentary
                admission issued for that event is an admission charge and enters the
                base, notwithstanding S-2.2. The test is applied event by event on the
                comp ratio printed on the manifest.

S-3.1           The county levies an events surcharge of 1.50 pct on the same base as
                S-2.1. The surcharge is remitted to the county and is not a city receipt.

S-5.1           A facility fee of 1.75 GBP is payable to the venue authority for each
                admission ISSUED, complimentary admissions included.
                The fee payable under this clause for any one event is capped at 12,000.00
                GBP. The cap is a term of this clause and is not waivable at filing.

Remittance Worksheet As Filed
----------------------------------------------------------------
The worksheet as the preparer computed it, one line per rule, in the sequence applied.
THE WORKSHEET DOES NOT STATE WHICH CLAUSE IT READ. It states a base value, a rate and
an amount; whether that base value is the base the ordinance defines is the question.

LINE: seq=1 rule=S-2.1 kind=ADMISSIONS_TAX authority=CITY base=PAID_FACE_PLUS_SERVICE base_value=217,245.50 rate=0.040000 amount=8,689.82
LINE: seq=2 rule=S-3.1 kind=COUNTY_SURCHARGE authority=COUNTY base=PAID_FACE_PLUS_SERVICE base_value=217,245.50 rate=0.015000 amount=3,258.68
LINE: seq=3 rule=S-5.1 kind=FACILITY_FEE authority=VENUE_AUTHORITY basis=ALL_ISSUED count=7426 per_ticket=1.75 cap=12,000.00 amount=12,000.00

  Authority                        Remitted
  CITY                             8,689.82
  COUNTY                           3,258.68
  VENUE_AUTHORITY                 12,000.00
  Total remitted                  23,948.50

Filing Notes
----------------------------------------------------------------
The venue's finance office queried the facility fee line and withdrew the query once the per-ticket schedule was produced.